

TL;DR
Being debt-free means your liabilities have reached zero. That is a powerful achievement, but it does not automatically mean you have built wealth. A household with no debt and little saved may still be financially vulnerable. Real financial strength comes from eliminating harmful debt while building cash reserves, retirement savings, investments and other meaningful assets.
The Celebration That Misses Half the Picture
Paying off debt deserves recognition. A cleared credit card balance means no more expensive interest draining your monthly income. A paid-off student loan or car loan removes a bill and creates room in your budget. Becoming mortgage-free can lower the amount needed to support your lifestyle for decades.
But debt-free is not the same as wealthy.
The celebration can become misleading when the entire focus is on reaching a liability balance of zero, with little attention paid to savings, investments or retirement security. Someone can make years of sacrifices to clear debt and still arrive with almost no emergency fund, no meaningful retirement balance and no assets that produce future financial stability.
Debt payoff removes weight. Wealth building adds strength. A complete plan must do both.
The Net Worth Formula Revisited
Net worth is calculated using a basic formula:
Net Worth = Total Assets − Total Liabilities
Assets include savings, investments, retirement accounts, home equity, business ownership and other items with financial value. Liabilities include credit card balances, loans, mortgages and other debts owed.
Suppose a person has no debt and $5,000 in a savings account. That person has a positive net worth of $5,000. Being free from monthly debt payments is valuable, but $5,000 may not cover a prolonged job loss, major home repair or long-term retirement needs.
Now consider someone with $180,000 invested for retirement and a $25,000 low-rate student loan balance. That person has a net worth of $155,000 before counting any other assets or debts. They are not debt-free, but their balance sheet is far stronger.
This does not mean debt should be ignored. It means liabilities are only one side of the equation. Financial security depends on what remains after debts are subtracted.
Two Debt-Free Stories With Very Different Outcomes
Consider Maya, a hypothetical 42-year-old who once owed $60,000 across student loans, a car loan and credit cards. She became intensely focused on eliminating every balance. For five years, she stopped retirement contributions, skipped investing and directed nearly every extra dollar toward debt.
At 42, Maya is finally debt-free. But she has only $12,000 in her retirement account and $4,000 in emergency savings. Her net worth is $16,000. She has achieved something difficult, yet she now needs to rebuild the investing years she missed.
Now consider Daniel, also hypothetical and also 42. He began with $60,000 in debt, but most of it was a moderate-rate student loan. He eliminated his credit card balance quickly, kept a cash emergency fund, contributed enough to his workplace retirement plan to receive the employer match available under his plan, and made steady payments on the remaining loan.
Daniel still owes $14,000. But he has $118,000 in retirement investments and $16,000 in savings. His net worth is $120,000.
Maya achieved zero debt. Daniel built a stronger overall position.
Neither person made a completely unreasonable choice. High-interest debt often deserves urgent repayment. But cutting off all asset building for years can leave someone debt-free without the resources needed for future stability.
The Opportunity Cost of Aggressive Debt Payoff
When Paying Off Low-Rate Debt Can Cost You
Extra debt payments provide a certain benefit: they reduce future interest according to the loan rate. That can be an excellent use of money when debt is expensive. Credit card balances charging high rates are especially damaging because the cost is immediate and difficult for investments to reliably beat.
Low-rate debt creates a more complicated choice.
Suppose a homeowner has a fixed mortgage at 3% and considers sending every spare dollar to principal. Paying extra will reduce interest and build equity faster. But directing all available money to a low-rate mortgage may mean missing years of retirement contributions or long-term investing.
An investment projection using a 7% annual return may show greater long-term growth than eliminating 3% debt early. However, that comparison must be treated honestly: the mortgage interest saving is predictable, while investment returns are not guaranteed. Investor.gov, the U.S. Securities and Exchange Commission’s investor education website, states that investments can lose value and no one can guarantee profits.
The issue is not that paying off a low-rate mortgage is wrong. For some people, the security of owning a home outright is worth more than the possibility of higher investment growth. The problem is paying off low-cost debt while leaving retirement accounts empty.
Missing an Employer Match Is Especially Costly
A workplace retirement match deserves separate attention. According to the IRS, a 401(k) plan may allow an employer to make matching contributions for employees who contribute through payroll deferrals. One example is an employer adding 50 cents for each dollar an employee contributes, subject to the plan’s terms.
When an available match is skipped so that every extra dollar can go toward moderate-rate debt, the borrower may be giving up employer contributions that would have added to retirement assets. That is very different from choosing between extra debt payoff and investing money with no employer contribution attached.
Before accelerating a low- or moderate-rate loan, check your workplace retirement plan rules. Securing an available match can be one of the first steps in building the asset side of your balance sheet.
The Right Balance: Build Assets While Reducing Liabilities
Debt payoff and asset building do not need to compete for every dollar.
A balanced approach begins with protecting against new debt. Keep or build an emergency fund alongside repayment, so an unexpected repair or medical bill does not go straight onto a credit card.
Next, prioritize costly balances. High-interest credit card debt and expensive personal loans can weaken net worth quickly through interest charges. Paying those down aggressively may offer more certainty than investing extra money while the balance remains.
At the same time, contribute enough to receive any employer retirement match available to you, subject to the plan’s rules and vesting schedule. Once expensive debt is controlled and a cash buffer exists, divide additional money between remaining debt reduction and long-term assets.
This approach changes the goal from “owe nothing at all costs” to “build the strongest possible financial position.” Zero debt can remain part of the plan without requiring years of zero investing.
How to See Your Full Financial Picture
Looking only at debt can make you feel successful the moment balances fall, or defeated while any debt remains. Neither view is complete.
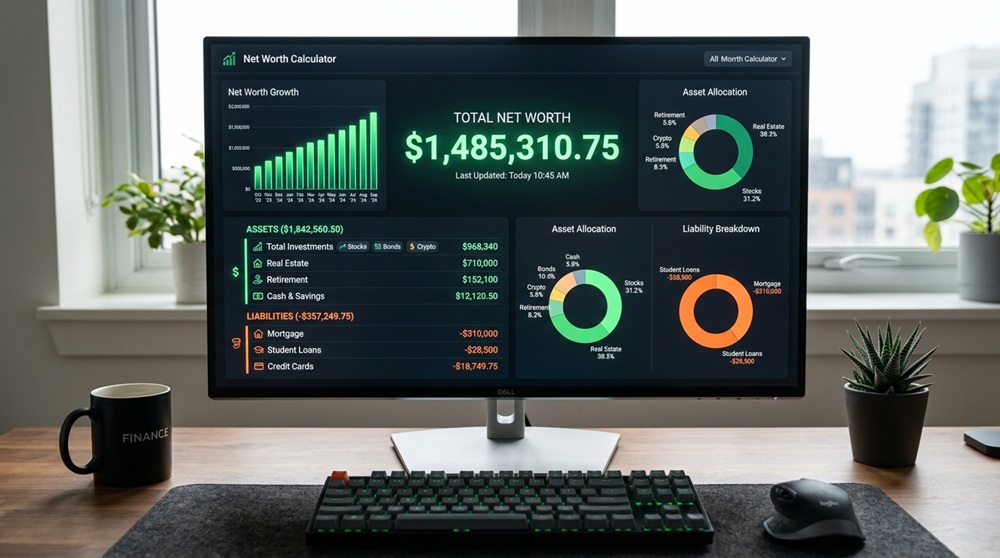
Enter your cash, retirement savings, investments, property value and other assets alongside every debt balance in one place. A calculator that helps you see your full financial picture shows the difference between being debt-free with few assets and being debt-free with a strong base of savings and investments.
For example, one person with zero debt and $8,000 in total assets has an $8,000 net worth. Another with zero debt, $120,000 in retirement savings and $30,000 in cash has a $150,000 net worth. Both are debt-free. Only the full balance sheet reveals how different their positions truly are.
Track the number every few months. Debt balances should decline, but assets should be growing too. Additional practical resources for understanding wealth measurement and personal finance basics are available through NetlyWorth.
Debt-Free Is a Starting Line, Not the Finish Line
Clearing debt can change your monthly budget and remove enormous stress. Celebrate it. Then put the freed payment to work. Build emergency savings, contribute to retirement accounts and invest for goals that debt payoff alone cannot fund. Financial security is not created by owing nothing while owning little. It is created when your liabilities shrink and your assets continue to grow.
